
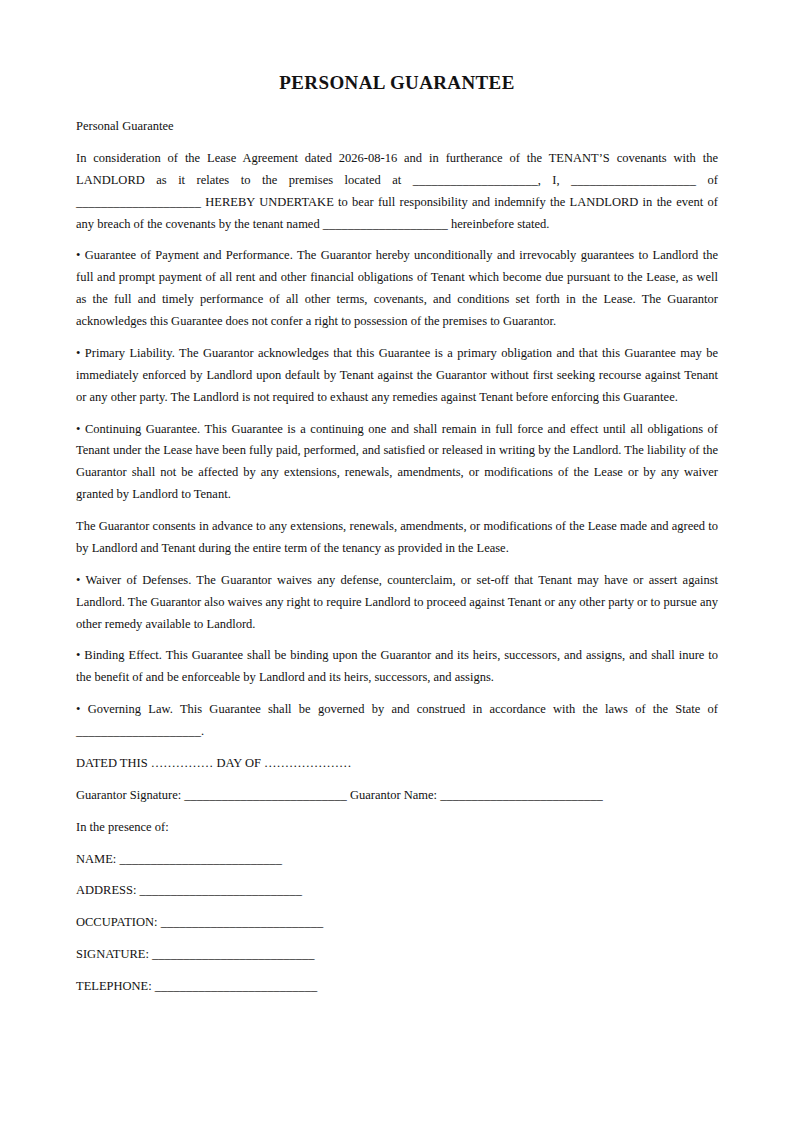
Personal Guarantee in Nigeria: Standing Behind Somebody Else's Debt
A personal guarantee is a promise by one person to pay another person's debt if they do not. Banks ask directors for them. Landlords ask company tenants for them. Suppliers ask for them before extending credit.
It is a short document with the largest consequences of anything on this site, because it reaches past a company and into somebody's own house and bank account.
What a Guarantee Actually Does
A guarantee is a separate contract from the debt it supports. The borrower owes the money. The guarantor promises that if the borrower does not pay, they will.
The practical effect for a director is that it undoes limited liability for that particular debt. The whole point of registering a company under the Companies and Allied Matters Act 2020 is that the company's debts are the company's. A director who signs a personal guarantee has voluntarily stepped outside that protection for the guaranteed amount, and no amount of company law helps afterwards.
A guarantee must be in writing to be enforceable. That is the one formality in your favour, and it means an oral assurance to a supplier is not a guarantee.
Guarantee or Indemnity
These get used interchangeably and they are not the same.
A guarantee is secondary. The guarantor's liability depends on the borrower's, so if the underlying debt is unenforceable, the guarantee generally falls with it.
An indemnity is primary. The person giving it takes on their own independent obligation, which survives problems with the main debt.
Lenders often draft a document that is both, because an indemnity closes the escape routes a guarantee leaves open. If you are being asked to sign, look for the words "as a primary obligor" or "by way of indemnity", because they change your position substantially.
The Terms That Decide How Bad This Is
Capped or unlimited. A guarantee limited to a stated sum is a very different risk from an all monies guarantee covering everything the borrower ever owes that lender. Negotiate a cap, and a separate cap on interest and costs.
Continuing or one off. A continuing guarantee covers future advances as well as the present one, so it keeps applying to borrowing you never saw.
Joint and several. Where several directors guarantee, joint and several liability means the lender can pursue any one of them for the whole amount. Being one of four guarantors does not mean being liable for a quarter.
Demand and enforcement. Whether the lender must pursue the borrower first, or can come straight to you. Most bank guarantees let them come straight to you, and that is usually what happens.
Duration and release. How the guarantee ends. Without a release mechanism, a director who resigns and sells their shares can remain personally liable for a company they no longer have anything to do with. This is the clause people most regret ignoring.
Variation, and the Rule That Can Discharge You
There is a long standing principle that a guarantor is discharged where the creditor materially varies the underlying contract without the guarantor's consent, because the guarantor is being held to a bargain they did not agree to.
Lenders know this, which is why well drafted guarantees contain a clause consenting in advance to variations, extensions of time, and further advances. If you are the guarantor, that clause removes one of your few protections and is worth negotiating. If you are the lender, its absence is a genuine risk when you later restructure the facility.
Before You Sign One
Read the underlying facility. You cannot assess a guarantee without knowing what is being guaranteed, including the interest rate and the default provisions.
Ask for a cap and an end date. The worst answer is no, and lenders more often agree than people expect.
Ask what happens if you leave. Get the release mechanism in writing.
Get independent advice. Especially where a spouse is being asked to guarantee, or where a family home is being offered as security alongside the guarantee.
Keep the original. Along with everything you were told about it.
And take seriously the possibility that you will actually be called on. Most guarantors sign believing the business will be fine. The ones who end up paying believed exactly the same thing.
Frequently Asked Questions About Personal Guarantees in Nigeria
Does a personal guarantee have to be in writing? Yes. A guarantee is unenforceable unless it is in writing and signed by the guarantor, which means a verbal promise to stand behind somebody's debt is not a guarantee.
Can a lender come after me before suing the company? Usually yes. Most commercial guarantees are drafted as payable on demand without requiring the lender to exhaust its remedies against the borrower first. Check whether your document says otherwise, because most do not.
I resigned as a director. Am I still liable? Very probably, unless the guarantee has a release mechanism and you used it. Resignation and selling your shares do not by themselves end a guarantee, and continuing guarantees can extend to borrowing taken after you left.
What happens if the lender changes the loan terms? A material variation made without the guarantor's consent can discharge the guarantee, but most guarantees contain a clause consenting in advance to variations and extensions. Whether that clause is present is one of the first things to look for.
Can my house be taken? A guarantee is a personal obligation, so a judgment against you can be enforced against your assets generally. Where the guarantee is supported by a mortgage or a charge over specific property, that property can be realised directly.
Getting Your Personal Guarantee Right
Read next: guarantees on a tenancy agreement, which follow the same rules. Where the guarantee supports a loan, the loan agreement is the other half of the arrangement.
Whether you are asking for one or being asked, the terms that matter are the cap, the duration, the release mechanism and whether it is continuing.
Answer a few questions and you will have a personal guarantee drafted for Nigerian use, with those terms set out plainly rather than buried, ready to download in Word and PDF.